Skip to content
OQAM
Menu

Funds / Mercurius Credit Fund

Mercurius Credit Fund (MCF)

An actively managed fund investing in Nordic corporate bonds with credit quality equivalent to ratings of A to BB, predominantly BBB. The fund’s structure and mandate are designed to capitalise on the way the Nordic credit market operates.

This is a marketing communication. Before making any final investment decision, read the fund’s information brochure, key information documents below and Important information.

Average annual return
6.61 %
vs 5.83 % target return
Since inception
+23.13 %
Target return
3m Stibor + 300 bps
over a market cycle
Volatility, since inception
1.47 %
has ranged between 1.25 and 1.47 %
Maximum drawdown
−0.65 %
from peak to trough
Management fee
0.80% fixed
no performance fee

As of 2026-09-30, share class A, since the fund's inception on 2023-07-07 – these details apply to all figures on this page unless otherwise stated. Returns are net of fees. The return, volatility and drawdown figures in the key figures panel are calculated using the fund’s monthly net asset values (NAVs). Past performance is no guarantee of future returns. The value of an investment in the fund can fall as well as rise, and you may not get back the full amount invested.

Returns in the context of risk

The fund is not managed against a benchmark index. We assess performance against its target return and the level of risk taken.

Annual excess return over Stibor

380 bps

vs 203 bps average credit spread

Morningstar Rating™

Overall rating, based on three years of data, among 132 funds in the category EAA Fund SEK Corporate Bond.

Sharpe ratio, 3 years
2.59
vs 0.96 for the peer group
Volatility, 3 years
1.54 %
vs 2.54 % for the peer group
Maximum drawdown, 3 years
−0.65 %
vs −1.61 % for the peer group

Performance

0 %5 %10 %15 %20 %25 %Jul 2023Feb 2024Oct 2024May 2025Jan 2026Sep 2026

Share class A, net of fees, since the fund's inception on 2023-07-07.

Monthly returns

Monthly returns
YearJanFebMarAprMayJunJulAugSepOctNovDecTotal
2026+0.42 %+0.67 %−0.65 %+0.93 %+0.70 %+0.51 %+0.00 %+0.35 %−0.36 %–––+2.59 %
2025+0.56 %+0.59 %−0.04 %−0.33 %+1.14 %+0.74 %+0.39 %+0.34 %+0.29 %+0.28 %+0.32 %+0.22 %+4.59 %
2024+1.20 %+0.45 %+1.03 %+0.62 %+1.13 %+0.64 %+0.96 %+0.68 %+0.82 %+0.38 %+0.75 %+0.27 %+9.30 %
2023––––––+0.33 %+0.69 %+0.84 %+0.69 %+1.20 %+1.15 %+4.99 %

Designed for the way the market works

The right size

The fund is large enough and, above all, active enough to secure attractive allocations in new issues, while remaining small enough to trade without moving prices against it. A fund that outgrows the Nordic credit market can be forced to buy whatever is available and may find few buyers when it needs to sell. That is why Mercurius Credit Fund closes to subscriptions when it reaches capacity.

Closes to new subscriptions at SEK 3–4 billion
Redemption on 90 days’ notice

A fund offering daily dealing in a market that cannot always provide daily liquidity needs to hold cash and bonds rated AAA or AA to meet unexpected redemptions. With a 90-day redemption notice period, the cash position in Mercurius Credit Fund reflects investment decisions rather than the need for a liquidity buffer, and the fund is normally fully invested. During periods of market stress, when other funds are forced to sell to meet outflows, the fund is less likely to need to sell and may instead be able to buy, as it did during the tariff-related market turmoil in April 2025. We believe this is essential to delivering attractive long-term returns.

Monthly dealing, 90 days’ notice for redemptions

The right mandate

Most capital in the Nordic credit market is managed under relatively narrow mandates. These may exclude bonds in certain currencies or from issuers without an external credit rating, or restrict investments to either investment grade or high yield. As a result, compensation for the same credit risk can vary across currencies and positions in the capital structure, while sound companies without an external rating often pay a premium. Our broader mandate allows us to invest where the fund receives the most attractive compensation for risk.

Explore how we have used the mandate over time in the investor portal

Concentrated but diversified across sectors

We include a bond in the portfolio only when its credit risk, terms or price compare favourably with alternatives in the market. A more concentrated portfolio gives each investment decision greater impact and helps us identify early signs that a company is performing differently from our expectations. We still diversify more broadly across sectors than the market as a whole, which is dominated by property companies.

Explore the portfolio’s history in the investor portal

Portfolio managers

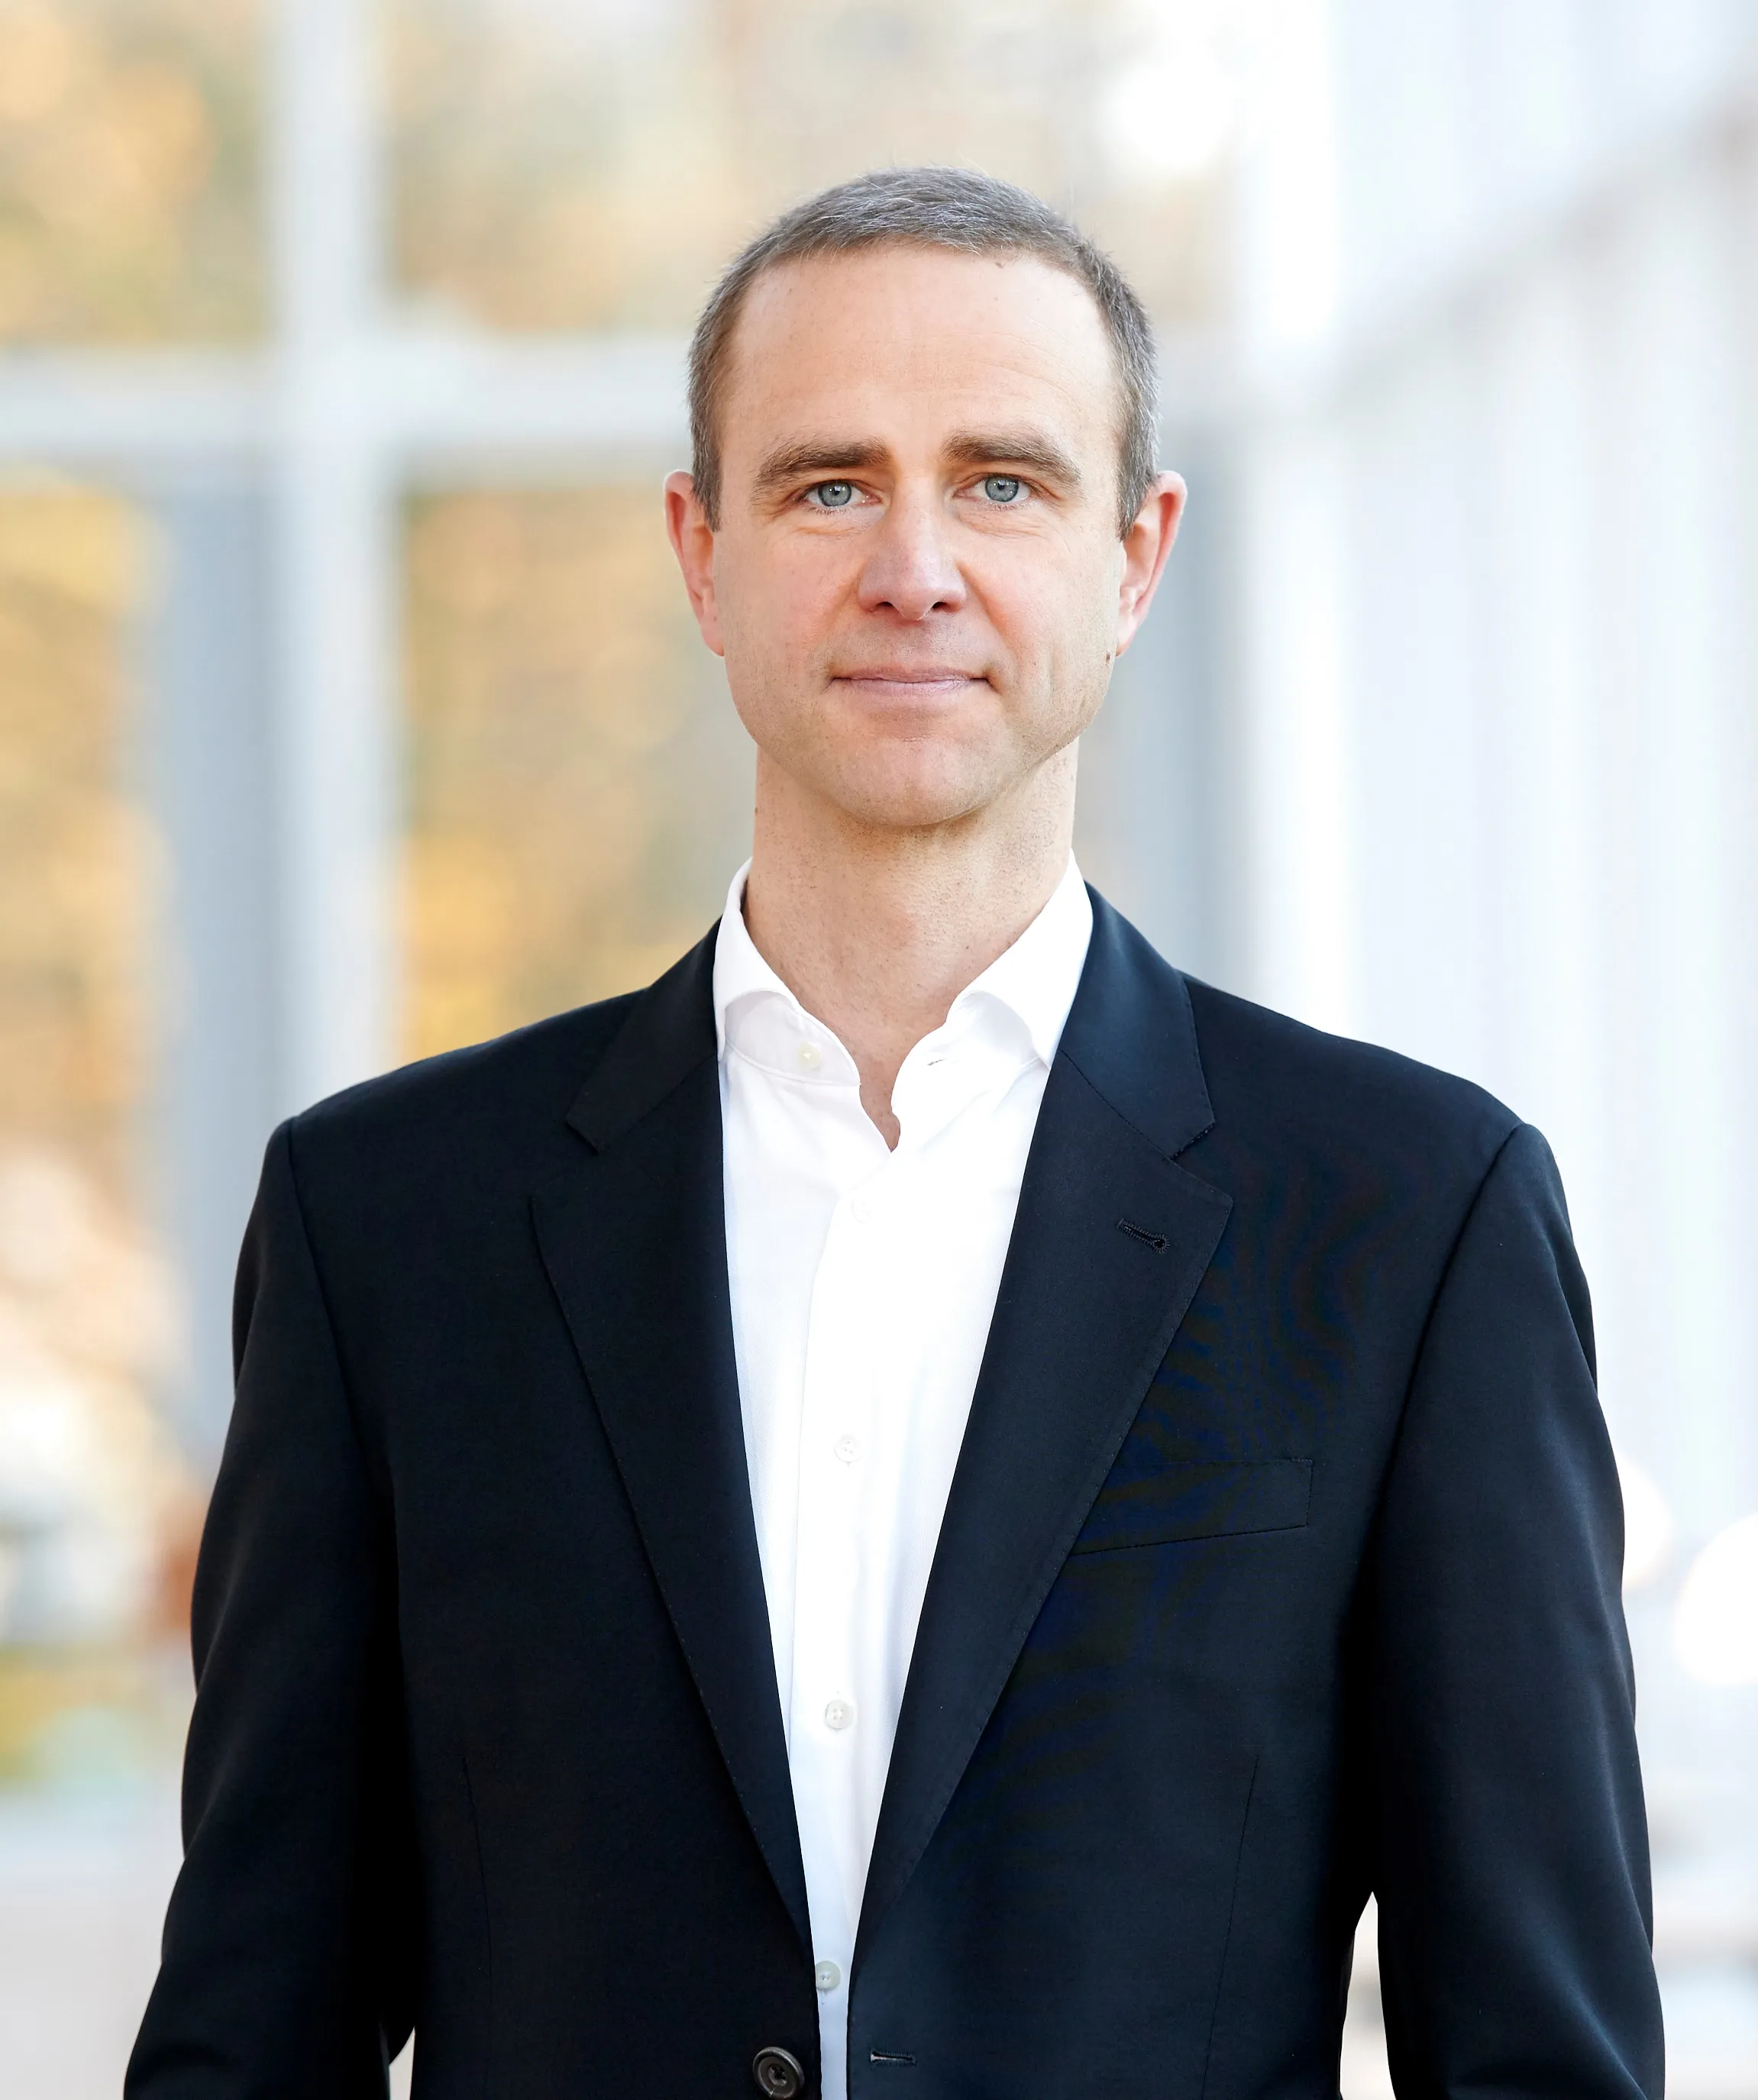
Christian Hjalmarsson

Lead portfolio manager

Christian Hjalmarsson

Christian has led the management of Mercurius Credit Fund since August 2023. Previously, he was chief dealer for Nordic corporate bonds at Nordea Markets, responsible for the bank’s SEK and EUR investment grade trading book through several challenging market periods. As a market maker, he focused on credits rated BB+ to AA, broadly the same segment in which the fund invests. His earlier work in foreign exchange also benefits the fund, which invests across currencies and hedges its currency exposure back to SEK.

+46 72 145 83 78 · ch@oqam.se · LinkedIn

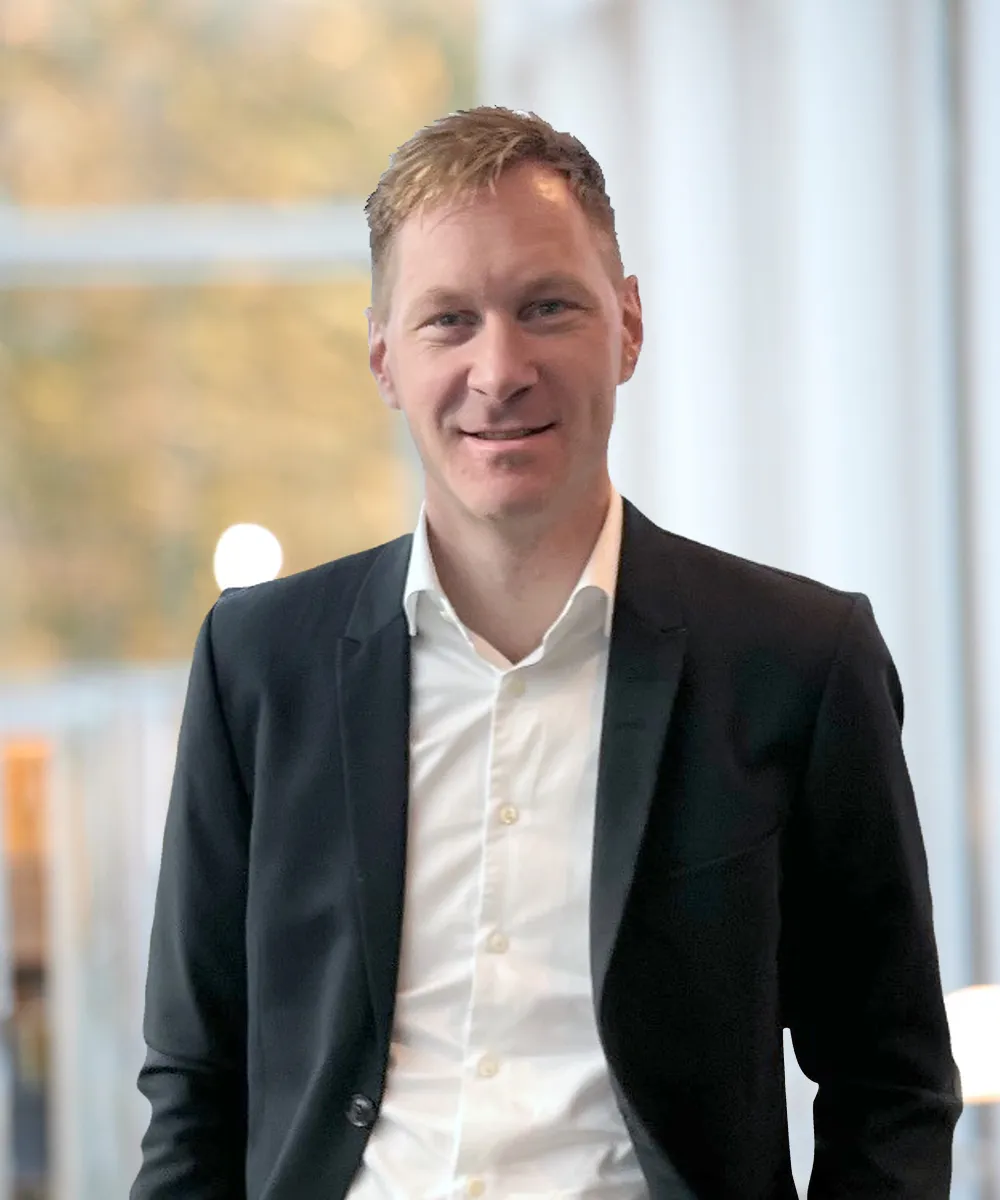
Andreas Olsson

CEO and portfolio manager

Andreas Olsson

Andreas is OQAM’s CEO and one of the portfolio managers of Mercurius Credit Fund. He has led asset management firms since 2003. He was one of the managers of Stella Nova, which was named Hedge Fund of the Year by Privata Affärer and Fondmarknaden.se in 2007. That year, Stella Nova’s managers also received the Star Hedge Fund Managers of the Year award from Dagens Industri and Morningstar. He has also managed quantitative investment strategies across multiple asset classes. He began his career as a market maker and derivatives trader.

+46 70 591 66 98 · ao@oqam.se · LinkedIn

How the fund is managed

Most of the fund’s return comes from a core portfolio of Nordic corporate bonds issued by around 30–35 companies that we know well and seek to hold over the long term. Credit quality is equivalent to ratings of A to BB, predominantly BBB. We actively manage this core portfolio, continually switching between an issuer’s bonds to find the best value across currencies, maturities and positions in the capital structure. This is complemented by active trading: shorter-term positions around core holdings, participation in new issues and opportunities created when flows drive prices. Returns come from Stibor, credit spreads and security selection, rather than interest rate positioning or currency exposure.

Our own credit assessment

Each holding is supported by two types of analysis. First, we assess the company’s creditworthiness, focusing on leverage, cash flow, ownership and access to other sources of funding. Second, we examine the bond’s terms, documentation and position in the capital structure, alongside its relative value compared with similar bonds. Our own credit assessment always underpins the investment decision, including where the company has an external credit rating.

Flows and pricing

In the Nordic credit market, prices are often driven more by flows and market participants’ buying and selling interests than by credit quality. Understanding these dynamics helps us identify relative value opportunities and act on them. Screen prices do not tell the whole story. We apply our knowledge of how the market operates to both the core portfolio and our active trading.

Compensation for risk

We take risk only when we believe the fund is adequately compensated. If compensation is too low, we prefer to move up in credit quality and forgo a few basis points of yield. When a bond becomes too expensive, we sell it even if we like the company, and look to buy it back when its price better reflects our credit assessment.

Facts and terms

Legal structure
Swedish special fund (AIF)
Alternative investment fund manager (AIFM)
FCG Fonder
Portfolio manager
OQAM
Independent valuation and risk control
FCG Fonder
Depositary
SEB
Auditor
PwC
Supervision
Finansinspektionen
Inception date
2023-07-07
Closes to new subscriptions
At SEK 3–4 billion
Minimum investment
SEK 1,000,000
Dealing
Monthly
Redemptions
90 days’ notice
Next dealing day
2026-10-30
Management fee
0.80%
Performance fee
None
Risk indicator
3 out of 7
SFDR
Article 6
ISIN A
SE0020540466
ISIN B (4% distribution)
SE0020540458
NAV A
123.1335
NAV B
108.0522

Frequently asked questions

What is the fund's target return?

The fund targets a return of three-month Stibor + 3% over a market cycle, net of fees.

Who is the fund suitable for?

The fund is designed for long-term capital that does not require daily liquidity, such as that of family offices, foundations, investment companies, pension foundations and companies investing surplus cash. It is suitable for investors with an investment horizon of at least three years who seek a medium-low level of risk. It is less suitable for those who need daily dealing or seek the returns associated with high yield investments.

How do I invest in the fund?

Subscriptions and redemptions are processed on the last banking day of each month. FCG Fonder must receive subscription requests no later than two days before the dealing day, and redemption requests no later than the last banking day three months before the dealing day (90 days’ notice). The minimum initial investment is SEK 1,000,000, with no minimum for subsequent investments. You can invest directly through FCG Fonder or via banks and investment platforms. Please contact us first if you would like us to explain the fund and its terms.

What is the difference between share classes A and B?

Share class B makes a quarterly distribution of 1% of the unit value, approximately 4% a year, payable in January, April, July and October. Distributions are automatically reinvested in the fund unless the unitholder has requested payment in cash. Share class A does not make distributions. The two share classes are otherwise identical.

What happens when the fund reaches its capacity limit?

The capacity limit protects our investors. The Nordic credit market is relatively illiquid and inefficient. If a fund outgrows what the market can accommodate, existing investors bear the cost through lower returns for the same level of risk or greater risk for the same return. The fund therefore closes to new subscriptions, including additional investments by existing unitholders. Redemptions continue as usual. The capacity limit is expressed as a range of SEK 3–4 billion: under the information brochure, the fund may close once assets exceed SEK 3 billion, and we expect it to close no later than when assets reach SEK 4 billion. FCG Fonder formally makes the decision and gives at least 30 days’ notice before it takes effect. When the fund closes, we will not launch an identical fund alongside it.

How does the fund approach sustainability?

The fund is classified under Article 6 of SFDR. It does not promote environmental or social characteristics and does not have sustainable investment as its objective. Sustainability risks are, however, taken into account in investment decisions, and exclusions apply to certain sectors and companies that breach specified international standards. Further details on exclusions and sustainability disclosures are available on the Sustainability page.

Talk to the portfolio managers

We welcome questions about the fund and the Nordic credit market. For a more detailed discussion of the trades that drove performance and what did not go as expected, we would be happy to arrange a meeting.

Contact the portfolio managers

Full transparency in the investor portal

  • The entire portfolio at issuer level, for every month-end since inception
  • Historical data since inception on credit ratings, sector exposures, credit spreads, yield to maturity and duration
  • Breakdown by currency, position in the capital structure, geography and maturity
  • Daily indicative performance
  • All monthly reports and historical NAV data
More about the investor portal
Request access